Ice Dams and Your Indiana Homeowners Policy
Why ice dams form, what a typical policy covers, and how to document the water damage they cause.
All 92 counties · Independent · Policyholder side
Your carrier accepted the claim, but the check won’t cover the repair. Indiana Insurance Appraiser builds an independent, line-by-line valuation of your loss and takes it through the appraisal clause already written into your policy.
Anatomy of a short claim
Most underpaid claims aren’t denied. They’re short: two roof slopes instead of four, gutters left off, a siding elevation that can’t be matched, no overhead and profit. Indiana Insurance Appraiser rebuilds the scope from your property, not from the carrier’s estimate, so the missing lines show up.
The chart is an illustrative hail claim on a central Indiana two-story. The carrier’s estimate totals $13,100. An independent line-item scope for the same storm comes to $33,830. That $20,730 difference is exactly the kind of gap the appraisal clause exists to resolve.
Start with an estimate reviewIllustrative hail claim · carrier vs. independent scope
Totals$13,100 → $33,830
Illustrative figures only, not a client result.
Eleven services
Every service is built around one job: a valuation of your loss that holds up in front of the carrier’s appraiser and an umpire. Start with a review, or bring us in once appraisal has been demanded.
 01
 02
 03
 04
 05
 06
 07
 08
 09
 10
 11
Five steps
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how an Indiana Insurance Appraiser file moves from the first call to the award.
We read your policy, the carrier’s estimate and your photos and tell you plainly whether appraisal fits.
Our own inspection, measurements and a line-item estimate priced for your Indiana ZIP code.
Appraisal is demanded in writing and Indiana Insurance Appraiser is named as your appraiser on time.
We work line by line with the carrier’s appraiser. Most of the gap is settled here.
Anything left goes to a neutral umpire. Two of three signatures set the amount of loss.
Four claim zones
An Indiana Insurance Appraiser has to know how each part of the state’s weather shows up on a roof and in an estimate. Pick a zone to see what we see there.
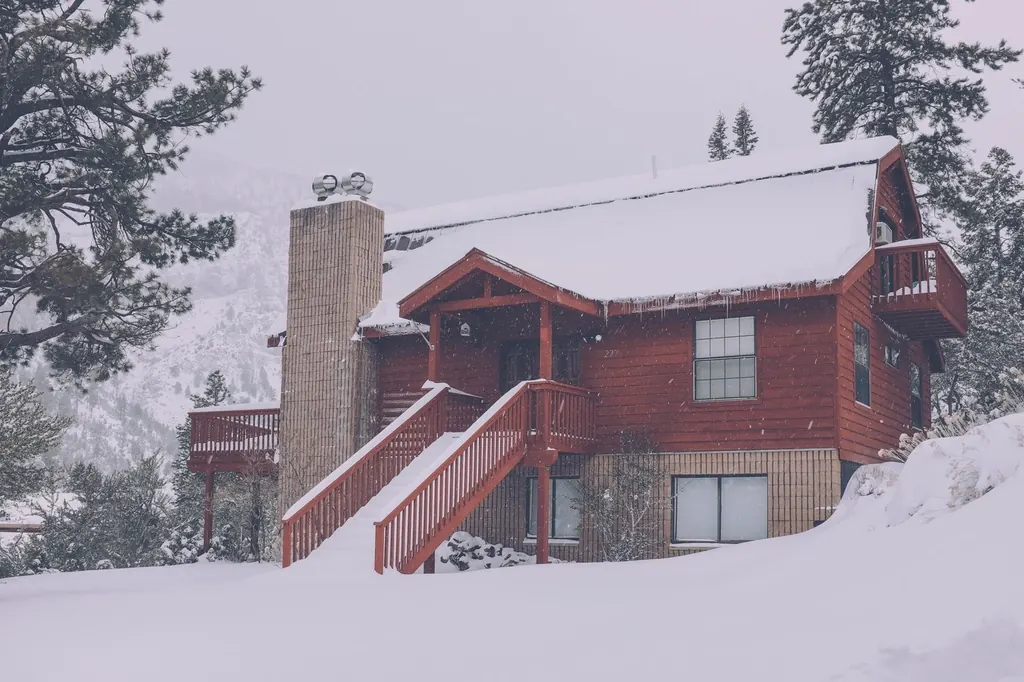
Lake County, Porter, LaPorte, St. Joseph and Elkhart counties get Indiana’s heaviest snow. Low-slope additions, porch roofs and pole barns take the load, and ice dams send meltwater into ceilings every winter.
City pages: Hammond, South Bend
Storms crossing from the west regularly drop hail on Marion and Hamilton counties. Fast-growing suburbs share discontinued shingle and siding lines, so matching disputes follow nearly every big storm.
City pages: Indianapolis, Carmel, Fishers, Kokomo
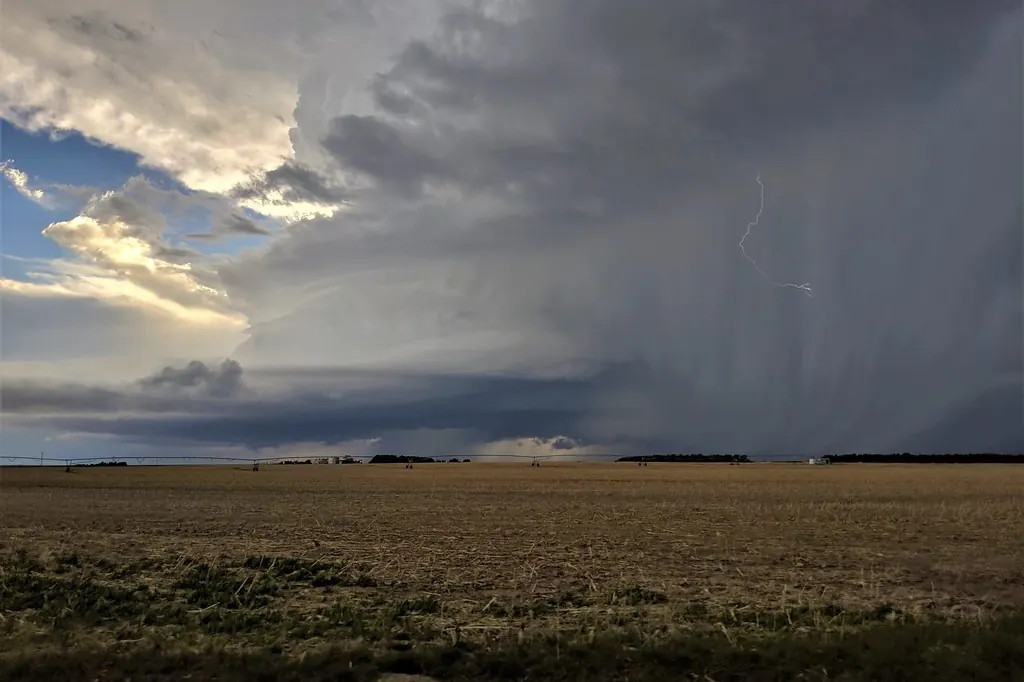
Open farmland lets storms build fast. Pole barns, grain bins and farmhouses in Tippecanoe, Vigo, Allen and the counties between them see wind and hail losses that need structure-by-structure valuation.
City pages: Lafayette, Terre Haute, Fort Wayne
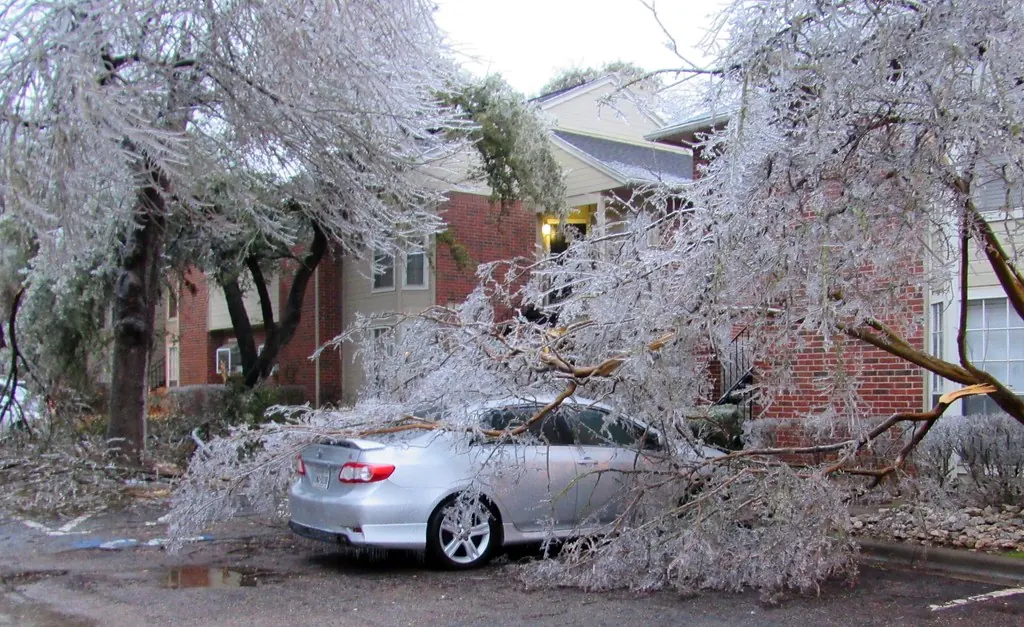
Wooded hills, limestone country and river towns. Ice storms bring limbs down on roofs, tornadoes like Henryville’s in 2012 cut long paths, and historic brick and stone homes need specialized pricing.
City pages: Evansville, Bloomington, Jeffersonville
Storm almanac
Every Indiana Insurance Appraiser file sits against this history. These events changed building codes, floodwalls and how carriers look at wind, water and ice in the state.
Record flooding swamped Evansville, Jeffersonville and river towns, leading to today’s floodwalls.
April 11 tornadoes struck northern and central Indiana, the deadliest tornado day in state history.
On April 3, tornadoes hit communities across Indiana, including Monticello and Madison.
A pre-dawn November 6 tornado tore through Vanderburgh and Warrick counties.
June floods hit central and southern Indiana; in September, Ike’s remnants brought widespread wind damage.
January freezing rain downed trees and power lines across southern Indiana.
A March 2 tornado devastated Henryville; a June 29 derecho swept the state.
A March 31 tornado struck Sullivan in the Wabash Valley.
Free & private
Run the numbers before you call. Every tool works in your browser, and nothing you type is stored or sent.
 EstimatorCalculator
 Calculator
 CalculatorPlannerChecklistEstimator
Quick check
Enter the two numbers you already have. If the difference is large, a conversation with an Indiana Insurance Appraiser makes sense. If it’s small, a documented supplement request may close it faster and for less.
The full claim gap and net recovery estimator adds appraiser and umpire fees and compares three scenarios.
Twelve city guides
We work in every county. These guides cover the cities where we handle claims most often, with local housing, storm history and the disputes we see there.
Straight answers
An Indiana Insurance Appraiser is the right call for some problems and the wrong one for others. We’ll tell you which on the first call.
FAQ
How appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your named appraiser we inspect, build an independent line-item estimate, negotiate with the carrier’s appraiser and present unresolved items to the umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside your policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the carrier’s estimate, and the gap to your contractor’s number is meaningful, roughly more than 10% or several thousand dollars.
Yes, on the amount of loss, once any two of the three panel members sign it. That’s why the file should be complete before appraisal is demanded.
Each side pays its own appraiser and usually half the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Yes. We cover all 92 Indiana counties, from Lake County to Posey County and from Fort Wayne to Jeffersonville.
Guides
Practical guides from the Indiana Insurance Appraiser team on policy language, documentation and strategy.
Why ice dams form, what a typical policy covers, and how to document the water damage they cause.
Narrow tornado paths and broad derecho swaths leave different evidence. Here is how to capture both.
When the original product is gone, a spot repair can leave a patchwork roof. What to know and what to document.
Start here
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure, no obligation.
